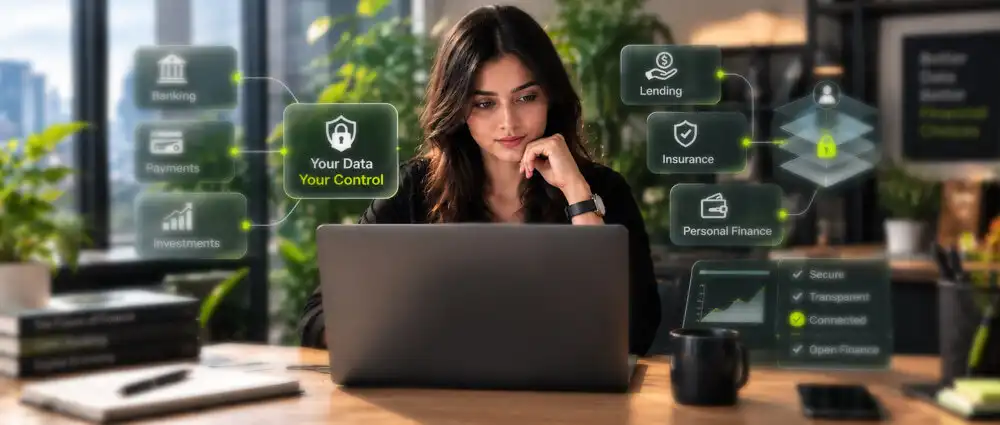
Financial data has traditionally remained with banks and financial institutions, limiting how easily customers can share it with other providers. Open finance changes this by allowing customers to authorize data sharing with banks, fintech companies, and other service providers. This development also increases the need for secure data connections and reliable applications, making software development services an important part of building and maintaining these solutions.
Consumers are showing greater willingness to share their financial information when it is protected. MX’s consumer research, based on a survey of more than 1,000 U.S. adults, found that 59% are willing to share their financial data if it is kept secure. This is a 10-point increase from the previous year. The survey also found that 82% want to see all their financial information in one place. These results show that consumers value both security and convenience when sharing their financial data.
A customer may have a bank account with one company, a loan with another, and insurance or investments somewhere else. Open finance makes it easier to share information from these different services with another provider, as long as the customer agrees.
APIs help banks and other financial companies exchange this information without asking customers to share their banking passwords. Customers can approve access to their records while keeping control over what they share.
The Bank for International Settlements explains that this type of data sharing can give customers more choices and help businesses offer new services. However, companies cannot use the information freely. They need customer permission and must follow data protection rules.
The question of financial data ownership is more complicated than deciding which organization stores the information. Banks collect and maintain records, fintech companies use them to provide services, and customers have rights over how their personal information is accessed and shared.
Financial services often involve more than one provider. A bank may hold the customer’s account records, while a data aggregator helps make those records available to another company. Fintech companies can then use the information to offer services such as budgeting tools or loans. APIs make it possible for these providers to connect and share data.
This does not mean every company has the same rights over the data. An aggregator may be involved in transferring information without using it to provide a financial product. A fintech company can process records for a specific service, but it cannot assume that accessing those records allows it to use them in other ways.
Customers may want to share their financial records when applying for a loan, using a budgeting app, or moving to another financial provider. Open finance allows them to give permission for this information to be shared. They can also withdraw that permission when they no longer need the service.
This ability to move information between services is known as data portability. It gives customers more flexibility when choosing financial products and switching providers.
However, access and ownership are different. A fintech company receiving customer permission does not gain unrestricted ownership of the information. Its use must remain within the agreed purpose and applicable legal requirements.
Financial information has become an important business resource because it helps companies understand customers, evaluate financial activity, and develop services. As more institutions adopt open finance, access to this information is becoming a source of competition.
Financial records support a wide range of services that customers use regularly. Lenders consider a person’s income and regular spending when assessing a loan application. Access to customer financial records gives businesses a better understanding of individual financial needs. They can use this information to review applications, adjust their services, and develop products that suit different customers.
This information can also help companies improve the services they already offer. Instead of providing the same options to everyone, they can use relevant financial details to make their products more suitable for different customers.
Sharing customer data requires investment from both sides. Banks are responsible for maintaining the systems that hold financial records, while fintech companies need technical connections to access information for their services. The question is how to split these costs.
Banks may expect fintech companies to contribute toward the costs of providing data access, including:
Fintech companies, however, may find these charges difficult to manage because:
These differences can affect how easily financial information is shared between providers and how much room smaller fintech companies have to introduce new services.
Financial data sharing involves more than giving another company access to customer records. Providers need to respect the customer’s choices and follow clear limits when handling that information.
Financial companies can use customer information shared by other providers to improve their services. This gives them more ways to develop products, reach new customers, and offer services based on what people need.
Access to customer-authorized information can improve several financial services.
Customers may not need to collect and send as many documents when applying for financial services. A lender, for instance, can verify income through a bank connection if the applicant gives permission.
Wider access to financial information creates more opportunities, but it also increases the responsibility to protect sensitive records. Businesses need to make sure that data sharing remains secure, controlled, and transparent.
With APIs, banks can share customer information with authorized providers while customers keep their banking passwords private. Authorized applications can request specific records through secure connections. However, businesses still need to protect these connections and the information they handle.
Some important security measures include:
Financial companies must also follow the data protection rules that apply in the markets where they operate. These rules can cover customer consent, data access, privacy, security, and responsibility when information is misused.
The European Union has proposed a Financial Data Access framework to cover more than payment account information. Under this proposal, customers would be able to share data from other financial services, including savings and investments.
This can be difficult for companies that serve customers in several countries. They may have to change how their systems handle data requests and customer permission to meet local rules.
The future of financial data involves several parties, and each has a different responsibility:
Open finance gives banks and fintech companies more ways to use financial information in their services. But access to customer records comes with responsibilities. Companies must respect customer permission, protect the information they receive, and follow the same fair rules when offering their services.
Open finance is giving banks and fintech companies new ways to work with customer information. This can lead to more financial services and choices, but it also puts responsibility on the companies handling that data. Customers should know who has access to their records and be able to change their permissions when they choose.
Building these services requires technology that can connect different systems, manage data securely, and support changing business requirements.
Looking to develop or improve your financial platform? Get in touch with Arpatech to discuss your requirements and explore the right software solutions for your business.
Open Finance can make personal budgeting easier by allowing you to connect information from different financial accounts in one place. A budgeting application can use authorized data to show your income, expenses, savings, and regular payments.
With all this information in one place, you can see how much you spend each month and which expenses take up most of your income. This can help you decide where to cut back, how much to save, and how to manage your monthly budget.
Banks store information about their customers, including account information and transaction records. These records are held by financial institutions, but customers still have rights over how their personal information is accessed and shared. The exact rights depend on the data protection laws that apply.
Open finance allows customers to give other providers access to selected financial records. A company receiving this information cannot use it for unrelated purposes and must follow the conditions of the customer’s permission.
Fintech companies use different ways to earn money from open banking services. Some charge customers a monthly or yearly fee to use budgeting and money management apps. Others charge fees for processing payments or providing services such as income verification and account information.
They can also earn through partnerships with banks and other financial providers. These arrangements may involve service fees, referral payments, or shared revenue. The terms depend on the services involved and the agreement between the companies.
Financial companies using cloud services need to know where customer information is stored and who can access it. They must follow data protection laws, ask customers before sharing their records, and limit third-party access to the information needed for a service.
Cloud systems also need proper security measures. Companies can protect financial records with encryption, strong login checks, and access limits. They should review their cloud providers, keep records of who accesses the data, and decide how long customer information needs to be stored.
Before we begin, please solve this quick math check to confirm you're human, and you'll be all set to start chatting with our AI assistant.
Stay connected with us to receive the latest information, updates, and insights from our world of innovation.
By entering your email address you will receive promotional updates.


© 2026 ARPATECH (ADVANCED RESEARCH PROJECTS & TECHNOLOGY)